 AutoTaxCalculator
How to write off a car for business: track your business miles, then deduct them with either the standard mileage rate or your actual costs times your business-use percentage. For 2026 the IRS rate is 72.5 cents a mile for January through June and 76 cents from July 1. Under actual expenses you add gas, insurance, repairs, registration and the like, plus depreciation, and claim the business share. Self-employed people report it on Schedule C, line 9. Commuting is never deductible, and employees generally can't deduct car costs at all.
"Write it off" gets used loosely. In tax terms it means deducting a cost from your business income so you pay less tax. With a car, the write off has three parts: the cost of driving it (fuel, insurance, upkeep), the cost of the car itself (recovered through depreciation over several years, or faster with special rules), and smaller items like parking and tolls. The IRS lets you claim all of that, but only for the business share, and only with records.
This guide is for sole proprietors, freelancers, gig workers, contractors and single-member LLC owners who file Schedule C. It covers how to write off a vehicle for business step by step: what counts as business driving, the two methods and how to choose between them, depreciation and Section 179, the heavy SUV rule, records, and what happens when you sell or trade in the car. All rules and numbers come from IRS Publication 463 (2025) and the IRS standard mileage rate page.
Business car tax deduction step 1: your business use
Every business car tax deduction starts with one number: what share of the car's use is for business. If you drive 20,000 miles in a year and 12,000 are for business, your business use is 60%. Under the mileage method you deduct those 12,000 miles. Under actual expenses you deduct 60% of the car's costs.
What counts as business driving:
- trips to clients, customers, job sites and suppliers,
- driving between two places of work in the same day,
- trips to a temporary work location,
- errands for the business, like going to the bank or the post office for business mail.
What doesn't: commuting. Publication 463 says you can't deduct the cost of driving between your home and your main or regular place of work, "no matter how far your home is," and not even if you make business calls on the way or bring a colleague and talk shop. If your home is your principal place of business, though, trips from home to clients and other work locations are business travel, not commuting. That's one of the biggest reasons a qualifying home office matters for people who drive a lot.
Personal trips, family errands and vacations don't count, even in a car you bought for the business.
Business vehicle deduction: two methods
The IRS gives you two ways to figure the business vehicle deduction. You can't mix them in the same year for the same car.
The standard mileage rate
You multiply your business miles by the IRS rate. The rate is meant to cover the whole cost of running the car, including depreciation, so it's the simplest car write off for business. The rates are:
| Period | Business rate |
|---|---|
| 2025 | 70¢ per mile |
| 2026, January 1 – June 30 | 72.5¢ per mile |
| 2026, July 1 – December 31 | 76¢ per mile |
The IRS raised the 2026 rate in the middle of the year, so for 2026 you need to know when your business miles were driven. 6,000 business miles in the first half and 6,000 in the second gives 6,000 × $0.725 + 6,000 × $0.76 = $8,910.
On top of the mileage amount, Publication 463 lets you deduct business parking fees and tolls, the business part of interest on a car loan if you're self-employed, and the business part of state and local personal property tax on the car. What you can't add: gas, oil, insurance, repairs, registration fees, depreciation or lease payments. The rate already covers them.
Rules that limit it:
- You must choose it in the first year. For a car you own, Publication 463 says you have to use the standard mileage rate in the first year the car is available for use in your business. After that you can switch between methods year to year. If you start with actual expenses, you generally can't switch to mileage later for that car.
- For a leased car, it's all or nothing. If you use the rate for a leased car, you must use it for the entire lease.
- Not with five or more cars at once. If you use five or more cars in the business at the same time, the standard mileage rate isn't allowed for any of them.
Actual expenses
You add up what the car really cost you during the year and deduct the business-use percentage. This is the method to use when a vehicle is expensive to buy or run, because the deduction tracks your real costs.
What vehicle expenses are tax deductible?
Publication 463 lists the actual car expenses you can count: depreciation, lease payments, registration fees, licenses, insurance, repairs, gas, garage rent, tires, oil, tolls and parking fees. Add them up, multiply by your business-use percentage, and that's the deduction. So what vehicle expenses are tax deductible in practice? Nearly everything it costs to own and run the car, but only the business share. Loan interest for a self-employed owner is deductible as a business expense in proportion to business use too.
What's not deductible under either method:
- Commuting miles, as above.
- Traffic fines. Publication 463 says you can't deduct fines or collateral you forfeit for traffic violations.
- Sales tax as an expense. Sales tax on the car is part of its basis and is recovered through depreciation, not deducted separately.
- The personal share of every cost.
One example of the full calculation, for a car used 75% for business with $2,400 of gas, $1,800 of insurance, $600 of repairs and $300 of registration: $5,100 × 75% = $3,825, before depreciation.
How to write off a vehicle for business: depreciation and Section 179
Under actual expenses, the car's purchase price isn't deducted all at once by default. It's depreciated over a five-year recovery period (spread over six tax years). But the law gives business owners faster options, and the limits differ by vehicle type, which is where most of the confusion about how to write off a vehicle comes from.
More than 50% business use is required. To claim Section 179 or accelerated depreciation on a car, Publication 463 says you must use it more than 50% for qualified business use. Below that, you're limited to straight-line depreciation.
Passenger cars, trucks and vans have yearly caps. For a passenger automobile placed in service in 2025, Publication 463 limits depreciation (including Section 179) to:
| Year | With bonus depreciation | Without bonus depreciation |
|---|---|---|
| 1st tax year | $20,200 | $12,200 |
| 2nd tax year | $19,600 | $19,600 |
| 3rd tax year | $11,800 | $11,800 |
| Each later year | $7,060 | $7,060 |
These caps apply at 100% business use and are reduced in proportion when business use is lower. So a $50,000 sedan used 80% for business placed in service in 2025 can take at most $16,160 in its first year ($20,200 × 80%), even with bonus depreciation. The IRS publishes new limits for each year's vehicles; check Publication 463 for the year you place the car in service.
Bonus depreciation is back at 100%. The July 2025 law made 100% bonus depreciation permanent for qualified property acquired and placed in service after January 19, 2025. For passenger cars the yearly cap above still applies, but for vehicles not subject to the cap it can mean deducting the whole business share in year one.
The heavy SUV and truck rule
The passenger car caps don't apply to every vehicle. An SUV, pickup or van rated at more than 6,000 pounds gross vehicle weight (and not more than 14,000) isn't treated as a passenger automobile for these limits. For those vehicles, Publication 463 caps the Section 179 deduction for an SUV at $31,300 for tax years beginning in 2025, but bonus depreciation isn't subject to the passenger car caps. That's why heavy SUVs and full-size pickups are popular with business owners: the business share of the cost can be written off much faster.
It's not a loophole for personal driving, though. The same more-than-50% business use test applies, the deduction is limited to the business share, and if business use later drops to 50% or less you'll owe some of it back (see below). Check the vehicle's GVWR on the door-jamb label, not its curb weight.
Commuting edge cases that trip people up
Most arguments with the IRS over a car write off for business come down to whether a trip was commuting. Publication 463 settles several common situations directly:
- Temporary work locations. If you have a regular place of work and drive to a temporary work location in the same business, the daily round trip from home is deductible, however far it is. Work at a location expected to last, and actually lasting, a year or less is generally temporary.
- Two places of work in one day. Driving from one job to another on the same day is deductible, whether or not it's the same employer. If you stop for personal reasons on the way, you can deduct only what the direct trip would have cost. Driving from home to a part-time job on a day off from your main job is commuting.
- A home office. If your home office qualifies as your principal place of business, daily trips between home and another work location in the same business are deductible. Publication 587 explains when a home office qualifies.
- Hauling tools. Carrying tools or instruments while commuting doesn't make the commute deductible. Only the extra cost, such as renting a trailer to tow them, is.
- Advertising on the car. Putting your logo or a sign on the car doesn't turn personal or commuting miles into business miles.
- Parking at your workplace. Parking at your own place of business is a commuting cost. Parking while visiting a client or customer is deductible.
- Car pools. A nonprofit car pool isn't deductible, and what passengers pay you isn't income. If you run a car pool for profit, the payments are income and the car expenses become deductible under the normal rules.
If you can show a trip fits one of the deductible patterns, write it in the log with its purpose. That note is what turns a disputed trip into a defensible one.
Using more than one vehicle
If the business uses two or more vehicles, figure the write off car by car. Each vehicle has its own business-use percentage, its own method choice and its own depreciation. You can use the mileage rate for one car and actual expenses for another.
The five-car rule only applies to cars used at the same time. Publication 463 explains that you aren't using five or more cars at the same time if you alternate between them: a salesperson who owns three cars and two vans and uses one at a time to call on customers can still use the standard mileage rate for all five. A landscaping business with five trucks working on the same days can't.
Replacing a car mid-year works the same way. The old car's business miles end on the day you stop using it, and the new car's start on the day you begin. Each is its own calculation on the return.
Business vehicle write off: which method gives more?
There's no single answer, but the pattern is consistent. The standard mileage rate tends to win for:
- cheap, efficient cars driven a lot of business miles,
- older cars that are already mostly depreciated,
- people who don't want to keep every receipt.
Actual expenses tend to win for:
- expensive vehicles, especially in their first years,
- vehicles with high running costs (big trucks, high insurance),
- heavy SUVs and pickups that can use bonus depreciation,
- cars with high business use but relatively few miles.
Remember the first-year rule. If you think you'll want the mileage method in later years, use it in the first year. Many people run both calculations in year one and pick the larger, knowing that choosing actual expenses (with accelerated depreciation) locks them out of mileage for that car later.
Worked examples
A rideshare driver with an efficient sedan
24,000 business miles in 2026, split evenly across the year: 12,000 × $0.725 + 12,000 × $0.76 = $17,820, plus tolls and parking. Under actual expenses, the car's yearly costs would have to be well over $17,820 at the business-use percentage to do better, which is unlikely for a small, efficient car.
A consultant with a $50,000 sedan, 2025, 80% business
Actual expenses for 2025: gas, insurance, repairs and registration of $6,000 × 80% = $4,800, plus first-year depreciation capped at $20,200 × 80% = $16,160. Total: about $20,960. With 14,000 business miles at 70¢ the mileage method would give $9,800. Here, actual expenses win in the first year.
A contractor with a 7,000 lb GVWR pickup, 90% business
The truck isn't subject to the passenger car caps. If it was acquired and placed in service after January 19, 2025, bonus depreciation can cover the business share of its cost in the first year, together with 90% of the running costs. The tradeoff: the basis is used up early, so later years have little depreciation left, and a sale may bring a taxable gain.
Records: how can you write off a car and keep the deduction?
The IRS's answer to "how can you write off a car?" always includes records. Publication 463 says you should keep a written record (a log, diary, trip sheets or a computer record) made at or near the time, plus receipts and other documentary evidence for expenses. For car use, the log should show for each business trip:
- the date,
- where you went,
- the business purpose,
- the miles driven.
Record the odometer at the start and end of the year too, so total miles and business percentage can be checked. Under actual expenses, keep the receipts for every cost you claim. A mileage app that records trips is a computer record, which Publication 463 accepts.
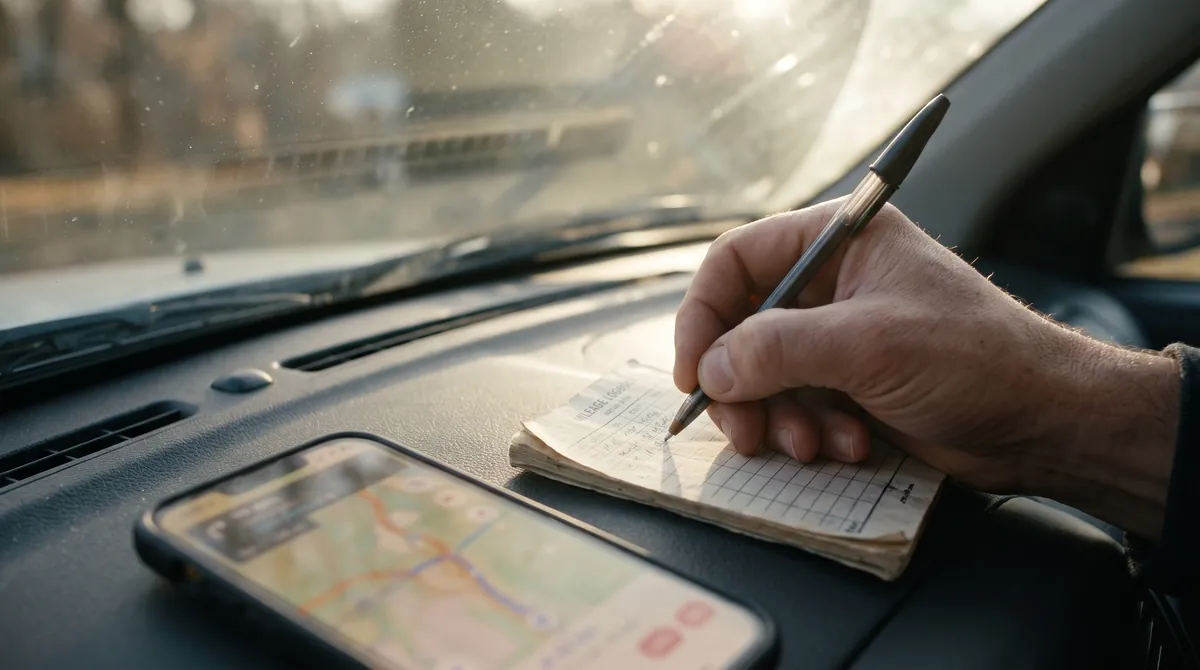
Without records, a business auto deduction is one of the first things to go in an audit, because it's easy to overstate. A log reconstructed months later is much weaker than one kept as you go.
Where the business auto tax deduction goes
- Sole proprietors: car expenses go on Schedule C, line 9. Complete Part IV with vehicle information unless you're filing Form 4562 for depreciation.
- Depreciation and Section 179: Form 4562, with vehicle details in Part V.
- Farmers: Schedule F, line 10.
- Employees: generally nothing. Unreimbursed employee expenses were miscellaneous itemized deductions, which Publication 463 says are no longer allowable. A few groups, such as Armed Forces reservists and qualified performing artists, have special rules.
So the business auto tax deduction is a self-employment benefit. If your employer requires you to drive, the way to get the cost covered is a reimbursement, not a deduction.
When you sell or trade in the car
Writing off a car lowers its tax basis, and that matters when you get rid of it.
- Depreciation reduces your basis. Even under the mileage method, part of each mile counts as depreciation (33¢ a mile for 2025), and Publication 463 says you must reduce the car's basis by that amount.
- A sale can produce a taxable gain. If you sell for more than the adjusted basis, the difference is a gain on the business share. With fast write-offs, the basis can be low even though the car still sells for a lot.
- Business use dropping to 50% or less triggers recapture. Publication 463 says that if business use falls to 50% or less in a later year, you must switch to straight-line depreciation and include the excess depreciation you took in income for that year.
- Trade-ins. Publication 463 says your basis in the new car is generally the adjusted basis of the old one plus what you pay.
For more on basis, see vehicle basis on taxes.
Leasing instead of buying
A leased car can be written off too. Under actual expenses you deduct the business share of the lease payments (minus an "inclusion amount" for more expensive cars) along with running costs. Under the mileage method, you must use it for the whole lease. The comparison is covered in is leasing a car a tax write off?
Mistakes that cost people the deduction
- Deducting commuting. Home to a regular office isn't business, however long the drive.
- Claiming 100% business use on the only family car. It invites questions, and it's rarely true.
- Mixing methods. With the mileage rate you can't add gas, insurance or repairs.
- Missing the first-year choice. Starting with actual expenses usually rules out the mileage rate for that car later.
- No log. Estimates written at tax time are weak evidence.
- Forgetting the mid-2026 rate change. Miles before July 1, 2026 use 72.5¢; miles after use 76¢.
- Searching for a "vehicle tax right off" shortcut. There isn't one. The write-off is the business share, documented.
Frequently asked questions
How do I write off a car for business?
Track business miles, then use the standard mileage rate or actual expenses times your business-use percentage, plus depreciation under actual expenses. Self-employed people report it on Schedule C, line 9.
What is the 2026 mileage rate for a vehicle write off?
72.5 cents per mile for January 1 to June 30, 2026 and 76 cents per mile from July 1 to December 31, 2026. For 2025 it was 70 cents.
Can I write off a vehicle for business if I also use it personally?
Yes, but only the business share. To write off vehicle for business costs, divide business miles by total miles and apply that percentage. For Section 179 and accelerated depreciation, business use must be over 50%.
Is a vehicle write off for business the same as deducting the purchase price?
Not exactly. A vehicle write off for business covers running costs each year, and the purchase price is recovered through depreciation, which can be accelerated with bonus depreciation or Section 179 within IRS limits.
Does the 6,000-pound SUV rule still apply?
Vehicles rated over 6,000 lbs GVWR (up to 14,000) aren't subject to the passenger car depreciation caps. The Section 179 deduction for such an SUV is capped at $31,300 for tax years beginning in 2025, and 100% bonus depreciation can apply to qualified property acquired after January 19, 2025. More than 50% business use is still required.
Can I take a car deduction for business as a W-2 employee?
Generally no. The car deduction for business use is for the self-employed. Employees' unreimbursed expenses aren't deductible under current law.
Can I deduct my car loan interest as a business?
If you're self-employed, the business share of car loan interest is a business expense under either method. The new personal car loan interest deduction on Schedule 1-A is for personal-use vehicles, and interest deducted on Schedule C can't be counted there too.
Can I switch from actual expenses to the mileage rate?
Generally not for the same car. You must choose the mileage rate in the car's first business year to be able to use it later.
The short version of how to write off a car for business: decide on the method in the first year, keep a real log, claim only the business share, and watch the depreciation caps. Done that way, a vehicle write off is one of the most valuable deductions a self-employed person has.
Sources
- IRS Publication 463 (2025): Travel, Gift, and Car Expenses
- IRS: Standard mileage rates (2025 and 2026)
- IRS: 2026 business standard mileage rate
Example figures are our own calculations from the IRS rates and limits. This article is general information, not tax advice. Editorial policy